
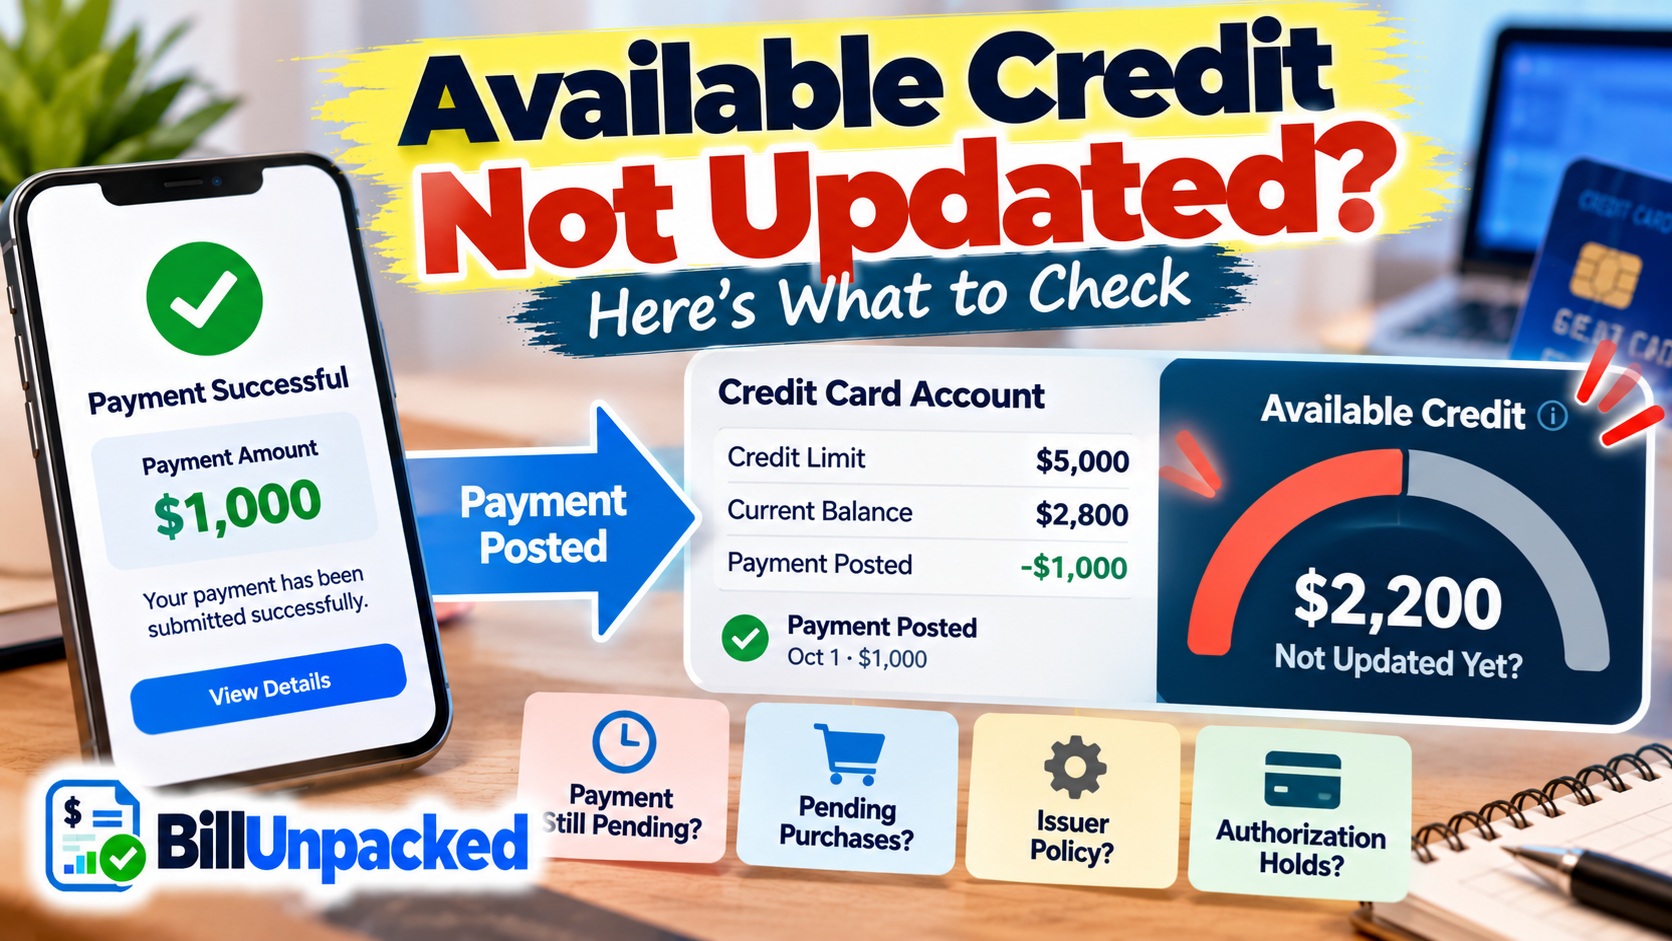
You paid your credit card—perhaps specifically to free up room for another purchase—but the available-credit number barely moved or did not change at all.
That can be confusing because payment status, account balance and available credit are related but are not identical account measurements.
Does a Credit Card Payment Instantly Restore Available Credit?
Not necessarily.
The Consumer Financial Protection Bureau specifically addresses consumers who have used all their credit and then made a payment. CFPB says how long it takes before the card can be used again depends on the card issuer’s policy, how much you paid and how much you want to charge.
Payment Posted vs Available Credit: What’s the Difference?
Money sent to card
Amount owed
Amount currently usable
A payment can affect what you owe without necessarily causing every number in the card account interface to update at exactly the same moment.
| Account Item | What It Tells You | What to Check |
|---|---|---|
| Payment status | Whether your payment is pending, posted, completed or returned. | Payment activity/history |
| Current balance | The amount the issuer currently displays as owed. | Recent payments, purchases and credits |
| Available credit | The amount of the credit line currently shown as available for use. | Credit limit, balance and other account activity |
| Pending purchases | Transactions that may still be processing. | Pending transaction section |
Why Hasn’t My Available Credit Increased?
1. The Payment Is Still Pending
Start with the payment itself. If it still says pending or processing, don’t assume the issuer has completed every account update associated with it.
Read: Credit Card Payment Pending? What It Means & How Long It Takes .
2. Your Issuer Has Not Yet Made the Credit Available for New Spending
Even after making a payment, CFPB says the time before you can use the card again depends on the issuer’s policy, the amount you paid and how much you want to charge.
If the payment appears correctly but available credit remains unchanged, check the issuer’s official account information or contact the issuer for the account-specific timing.
3. New or Pending Purchases Are Using Credit
Look at what happened after the payment.
For example:
- Credit limit: $2,000
- Balance before payment: $1,800
- Payment: $500
- New purchases after payment: $200
Ignoring other account adjustments, you should not expect the full $500 payment to translate into a permanent $500 increase in available credit if new spending is simultaneously using part of the line.
4. An Authorization Hold Is Still Affecting the Account
Some purchases begin with an authorization rather than immediately becoming a final posted transaction. Hotels, rental cars, restaurants and fuel purchases are common situations where the authorized amount and final amount can differ.
Check the pending section before assuming the payment itself is the problem.
5. The Payment Was Returned or Reversed
A payment may initially appear and later be removed if it does not remain successfully credited.
If your payment status says returned, reversed or similar, read: Credit Card Payment Reversed? What It Means & What to Do .
6. The Payment Itself Is Missing
If you cannot find the payment at all, this is a different problem from an available-credit delay.
Use: Credit Card Payment Not Showing? What to Check .
Available Credit Checker
Use this calculator to compare a simple expected available-credit figure with what your card currently displays.
Should My Available Credit Have Changed?
This calculator provides a mathematical comparison only. It cannot access or diagnose your credit-card account.
What If My Payment Is Posted but Available Credit Still Hasn’t Updated?
This is the point where you should separate two questions:
- Was my payment properly credited?
- When will the issuer let me use the corresponding credit again?
Federal Regulation Z generally requires a conforming payment to be credited to the account as of its date of receipt, subject to the regulation’s requirements and exceptions.
However, the official interpretation explains that this rule does not require the creditor to visibly post the payment on a particular date.
Can I Make a Large Purchase While Waiting?
Do not assume that a lower balance automatically means a particular purchase will be approved.
Check the available credit displayed by your issuer. If you need to make an important transaction that approaches the available amount, contact the issuer for account-specific information.
Should I Make Another Payment?
Not simply because available credit has not increased.
First verify whether the original payment is pending, posted, missing or returned. Sending another payment without understanding the first one could create an unintended overpayment.
If payments and other credits exceed what you owe, the account can develop a credit balance. CFPB explains that a credit balance is money the credit card company owes you.
What Should I Check Before Calling the Card Issuer?
- Your credit limit
- Current balance
- Available credit
- Payment amount
- Payment status
- Payment confirmation number
- Pending transactions
- Recent purchases
- Returned or reversed payments
- Recent refunds or account credits
Having these numbers in front of you makes it much easier to explain the specific mismatch.
Available Credit vs Credit Balance
These terms sound similar but mean different things.
| Term | Meaning |
|---|---|
| Available credit | The portion of the credit line currently shown as available for use. |
| Credit balance | A balance where credits exceed the amount owed, meaning the card company owes you money. |
If your account has gone below zero after a refund or overpayment, see: Negative Balance on Credit Card? What It Means .
Bottom Line
If your available credit is not updated after a payment, don’t assume either that the payment failed or that the issuer must restore the credit immediately.
Check the payment status, current balance, available credit and pending transactions separately. CFPB says the time before you can use the card again can depend on the issuer’s policy, how much you paid and how much you want to charge.
If the payment itself is missing or reversed, troubleshoot that payment first. If the payment is correctly reflected but you still cannot explain the available-credit figure, contact your card issuer.
Authoritative Sources
Consumer Financial Protection Bureau:
I used all my credit and made a payment. How long does it take before I can use the card again?
Consumer Financial Protection Bureau — Regulation Z:
§ 1026.10 — Payments
Consumer Financial Protection Bureau:
What is a credit balance on my credit card bill?
Independent consumer information: BillUnpacked is not a bank, lender, card issuer or payment network. This page provides general educational information. Your card issuer’s records, account agreement and current policies determine your actual balance and available credit.