
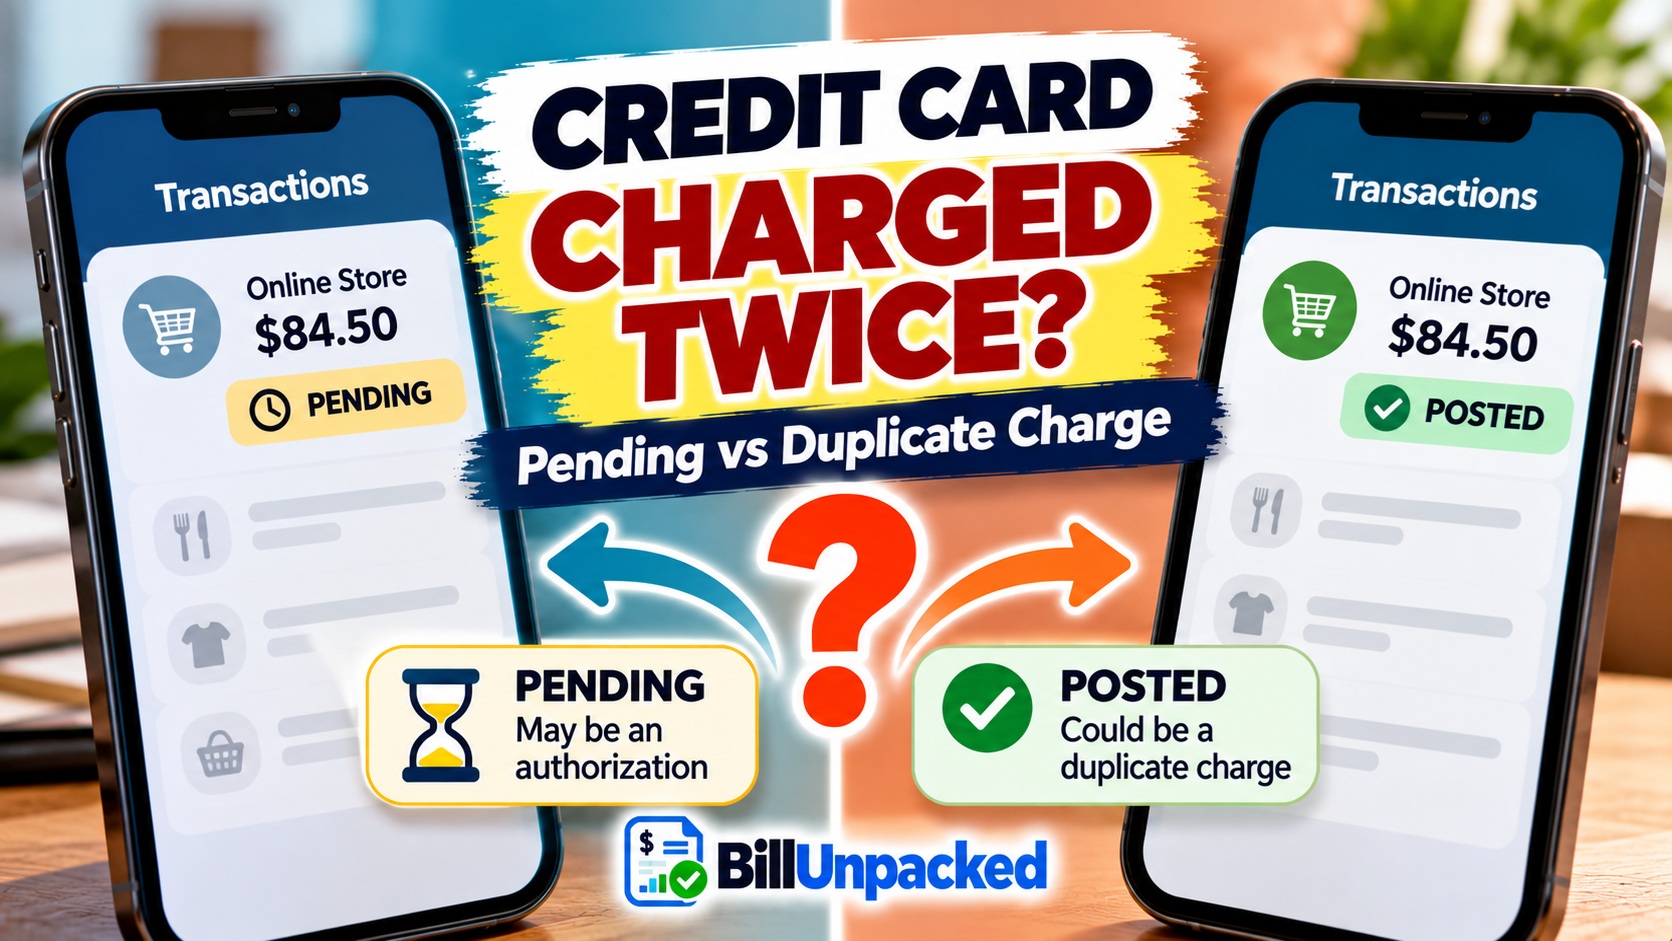
If your credit card appears to be charged twice, check the status of both transactions before assuming you paid twice. One pending authorization plus one posted charge can sometimes make a single purchase appear twice temporarily. But if two transactions for the same purchase have both posted, investigate them as a possible duplicate charge.
Why Does the Same Credit Card Purchase Appear Twice?
Credit-card transactions can move through more than one processing stage.
A merchant can first request an authorization. The transaction may then appear as pending before the final transaction posts.
Depending on how your issuer displays activity, the pending authorization and final posted transaction can sometimes appear separately for a period of time.
That is why transaction status matters just as much as the merchant name and dollar amount.
Pending + Posted vs. Two Posted Charges
| What You See | What It Could Mean | What to Do |
|---|---|---|
| 1 pending + 1 posted | Possible authorization plus final transaction | Monitor the pending entry and verify the purchase |
| 2 pending | More than one authorization attempt may have occurred | Check whether you attempted payment more than once |
| 2 posted | Possible true duplicate billing | Compare receipts and contact merchant/issuer |
| 1 posted + 1 reversed | Earlier authorization may have been reversed | Confirm only one completed charge remains |
What Should I Check First?
Check Whether Both Charges Are Actually Posted
Open each transaction and look for its status.
Common labels include:
- Pending
- Processing
- Posted
- Completed
- Reversed
The exact wording depends on your card issuer.
If one transaction is pending, read: What Is a Pending Charge on a Credit Card?
Compare the Merchant Names
Make sure both entries really came from the same merchant.
Merchant descriptors can sometimes differ from the store name you recognize, so compare the transaction details with your receipt or order confirmation.
Compare the Amounts
If both entries have the same amount, that can support your investigation—but matching amounts alone do not prove duplicate billing.
Restaurants, hotels and other merchants may also have an initial authorization amount that differs from the final charge.
Check Whether You Tried to Pay More Than Once
Think back to the checkout.
Did you:
- Click the payment button twice?
- Receive an error and try again?
- Refresh the checkout page?
- Use the card again after a decline?
- Place a second order?
Multiple payment attempts can complicate the transaction history.
If checkout failed, see: Credit Card Charged but Order Didn’t Go Through?
Duplicate Charge Checker
Use this tool to organize what you’re seeing. It does not access your card account or determine whether a transaction is legally a billing error.
Do These Look Like Duplicate Charges?
Enter the two transaction amounts and statuses.
Does Pending + Posted Mean I Paid Twice?
Not necessarily.
A pending transaction represents activity that has not yet reached the same final status as a posted transaction.
If the merchant, amount and timing match, the pending entry may be related to the authorization for the transaction that ultimately posted.
Monitor the pending entry and check whether it is later released, disappears or otherwise changes.
Two lines in your card app do not necessarily equal two finalized charges. The stronger duplicate-charge signal is two completed/posted transactions tied to one purchase.
What If Both Charges Are Pending?
Two pending transactions can occur after multiple authorization attempts, but the exact reason depends on the merchant and payment processing.
Check whether you attempted the transaction twice and ask the merchant whether it sees:
- One order or two
- One authorization or multiple authorizations
- One captured payment or multiple payments
Do not assume that both pending entries will disappear, and do not assume both will post.
What If Both Charges Have Posted?
If both transactions are posted and both relate to a single purchase, save your receipt and investigate promptly.
The FTC specifically lists being charged more than once for something as a reason a card transaction may be incorrect under the credit-card billing-error process.
You can contact the merchant to ask it to correct a clear duplicate, but also keep your card issuer’s dispute deadline in mind.
Should I Contact the Merchant First?
For a merchant you recognize, it can be useful to ask whether it sees one completed payment or two.
Have ready:
- Your receipt or order number
- Transaction amounts
- Transaction dates
- Status of each transaction
- Screenshot of the two entries
But do not let a lengthy merchant conversation cause you to miss the applicable card-dispute deadline.
FTC guidance recommends reporting disputed card charges promptly and preserving the written dispute process when applicable.
What If the Merchant Says It Only Charged Me Once?
If two transactions have posted but the merchant says it received only one payment, contact your card issuer and provide the merchant’s response.
The issuer can investigate the transactions using information not visible in your consumer-facing transaction list.
Keep copies of any emails or merchant support messages.
What If One Duplicate Charge Disappears?
Check its final status.
If one entry was pending and later disappeared or became reversed while one legitimate transaction remains posted, you may have been seeing an authorization rather than two completed charges.
For more detail: Why Did My Pending Credit Card Charge Disappear?
What If the Amounts Are Slightly Different?
Do not automatically classify them as duplicates.
Check for:
- Restaurant tips
- Adjusted final totals
- Partial shipments
- Separate orders
- Temporary authorization amounts
- Other merchant adjustments
For example, a restaurant authorization may differ from the final amount after an authorized tip is included.
Can a Duplicate Charge Be Disputed?
Yes, a genuine duplicate credit-card charge can fall within the federal billing-error process.
FTC guidance expressly includes being charged more than once for the same thing among examples of disputable billing errors.
The CFPB advises consumers to call the card company or file a dispute online, and also send the written notice promptly to preserve federal rights.
What Happens After a Written Billing-Error Notice?
According to current CFPB guidance, after receiving the written notice the issuer generally has 30 days to acknowledge it, unless the required resolution procedures have already been completed.
It then has up to two billing cycles to finish investigating the dispute.
While the qualifying billing error is being investigated, CFPB says you remain responsible for paying the correct, undisputed charges on time.
What Evidence Should I Keep?
Save These Records
- Purchase receipt
- Order confirmation
- Screenshot of both transactions
- Merchant name and transaction amounts
- Order number
- Merchant emails or support messages
- Refund confirmation if one was issued
- Your dispute correspondence
FTC guidance recommends including copies rather than original supporting documents with a written billing-error dispute.
What If I Don’t Recognize Either Charge?
That is different from a known purchase appearing twice.
If you did not authorize the transaction, contact your card issuer promptly using the official number on your card, statement or issuer website/app.
An unfamiliar charge can involve an unauthorized transaction rather than ordinary duplicate merchant billing.
5-Minute Duplicate Charge Checklist
Check These in Order
- Open both transaction details.
- Check whether each is pending or posted.
- Compare the merchant descriptors.
- Compare the exact amounts.
- Find the original receipt.
- Check whether you attempted payment more than once.
- Look for multiple order numbers.
- Check whether one entry is reversed or released.
- If both are posted, ask the merchant whether it received two payments.
- Contact the card issuer promptly if a duplicate remains.
- Preserve the applicable written billing-error deadline.
Bottom Line
If your credit card appears to have been charged twice, the first question is not whether the amounts match. The first question is whether both transactions are actually posted.
One pending authorization plus one posted transaction can sometimes make a single purchase look duplicated temporarily. But if two completed transactions relate to one purchase, document the issue and contact the merchant and card issuer promptly.
Authoritative Sources
Federal Trade Commission:
Using Credit Cards and Disputing Charges
Federal Trade Commission:
Sample Letter for Disputing Credit and Debit Card Charges
Consumer Financial Protection Bureau:
How to Fix Mistakes in Your Credit Card Bill
Consumer Financial Protection Bureau:
How Do I Dispute a Charge on My Credit Card Bill?